The ECB Paused at 2.50 Percent. December Is Circled, and France Is in the Room.
Christine Lagarde delivered a unanimous pause in the European Central Bank's deposit rate at 2.50 percent on Oct. 29 only after policymakers debated an immediate increase, deferring until December a reckoning with 3.8 percent eurozone inflation, surging energy costs and French borrowing rates above 5 percent for the first time since 2002.
3 minute read
PARIS — When President Christine Lagarde stepped before reporters at her Oct. 29 news conference, she delivered a unanimous decision by the European Central Bank that projected calm while concealing a live dispute inside the room. Officially, policymakers left the bank’s deposit facility rate untouched at 2.50 percent. Yet before settling on a pause to await fuller data, Ms. Lagarde disclosed afterward, the Governing Council had actively debated an immediate rate increase. That truce holds only until the council reconvenes on Dec. 17, and the futures market has already taken sides: on the day of the decision, traders priced roughly an 82 percent probability of a quarter-point rise, to 2.75 percent.
The decision to wait followed increases of 25 basis points in June and again in September, which left the main refinancing rate at 2.65 percent and the marginal lending rate at 2.90 percent. What stayed the council’s hand in October was the uneven anatomy of the price pressures confronting it. Headline eurozone inflation climbed to 3.8 percent in September from 3.2 percent in August, a jump driven overwhelmingly by energy inflation at 18.9 percent, while inflation excluding energy edged up only modestly, to 2.3 percent. Ms. Lagarde said the second-round effects the bank fears — higher energy costs feeding into wage demands — remained for now no greater than the bank had already anticipated. As evidence, she pointed to the ECB’s wage tracker, which indicates wage growth of 2.5 to 2.8 percent in the remaining months of 2026.
The tightening that happened anyway
Even with official rates unchanged, borrowing across the currency bloc has grown costlier on its own. Financing conditions have tightened since the bank’s September meeting, with average 10-year sovereign yields across the eurozone rising by about 35 basis points between the September projection cutoff and the October decision — doing part of the council’s work in advance and easing the pressure to move immediately. In its policy statement, the bank held fast to the formula now guiding its choices: decisions taken meeting by meeting and data by data, with headline inflation expected to stay well above the 2 percent target in the coming quarters before the energy component fades.
France, unavoidably
Looming over the deliberations in Frankfurt is the eurozone’s second-largest economy. On Oct. 21, French government borrowing rates climbed past 5 percent for the first time since 2002, a threshold that drew pointed questions for Ms. Lagarde at her news conference. The fiscal standoff has only deepened since: France’s National Assembly rejected the government’s 2027 budget outright, leaving the Senate to take up the original text on Friday in a country whose finances anchor half the eurozone’s political risk. Though the ECB does not draft French budgets, bond markets price them against its policy, turning every basis point of wider French spread into an unvoted tightening borne unevenly by the member state least able to absorb it.
Those crosscurrents give the December meeting a double weight. Policymakers must judge whether the energy shock is a one-off level shift they can look through or a broader spiral they must lean against — and they must make that call under a president who has already announced she is stepping down. Ms. Lagarde’s departure, and the succession it opens, is reported separately by this desk. Across the Channel, the Bank of England, wrestling with the same energy arithmetic, renders its own decision on the very same day, Dec. 17. More of the desk’s European coverage appears in the Global News section.
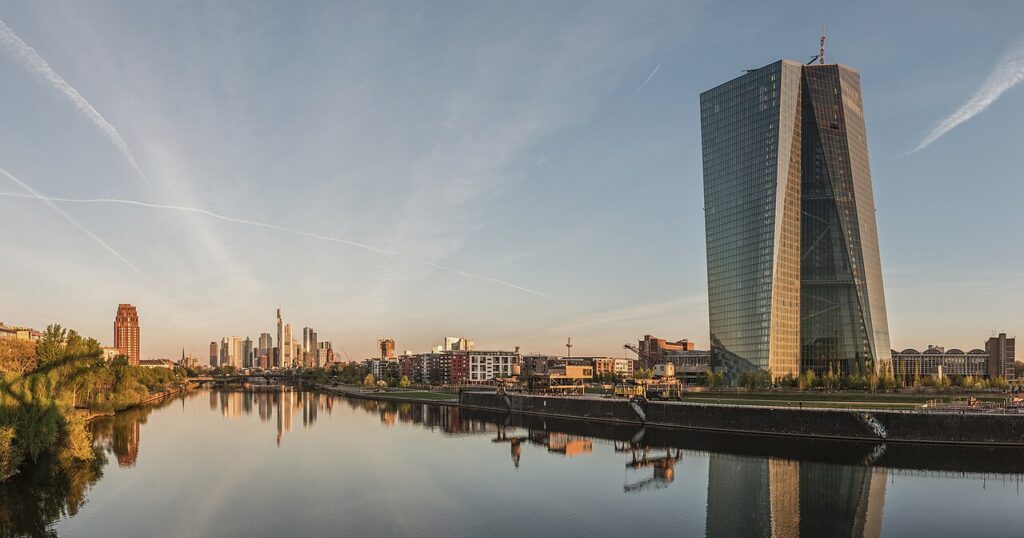
Featured image: The seat of the European Central Bank in Frankfurt at dawn. Photo: DXR, CC BY-SA 4.0, via Wikimedia Commons.
Sources & notes
- The Oct. 29 decision (deposit facility 2.50 percent; main refinancing 2.65 percent; marginal lending 2.90 percent; unanimous), the disclosure that a rise was debated, the energy-risk assessment and the meeting-by-meeting formula: European Central Bank monetary policy statement and President Lagarde’s press conference, Oct. 29, 2026, as reported by FXStreet and AJ Bell the same day.
- September inflation (headline 3.8 percent; energy 18.9 percent; excluding energy 2.3 percent), the June and September increases, the rise of about 35 basis points in average 10-year sovereign yields, the wage tracker (2.5 to 2.8 percent) and the expectation of a 25-basis-point rise on Dec. 17: UOB Global Economics & Markets Research macro note, Oct. 30, 2026, on the ECB’s published data.
- The futures pricing of roughly an 82 percent probability of a December rise to 2.75 percent: market pricing as of Oct. 29, 2026, reported by EBC Financial Group.
- French borrowing rates surpassing 5 percent on Oct. 21, the first time since 2002: Le Monde, Oct. 30, 2026.
Orlando Citizen by email
The weekly edition, in your inbox
One email, every Saturday: the week’s edition of Orlando Citizen — the week’s stories, rankings and winners, gathered in one place. Free, and you can unsubscribe at any time.
Related Stories
Editor’s Picks
Spotted an error? Tell us — corrections · How we rank